Show table of contents · 11 sections▾
Nothing here is legal advice. The frameworks below are consistent with widespread practice; consult your attorney for anything case-specific.
The Core Choice
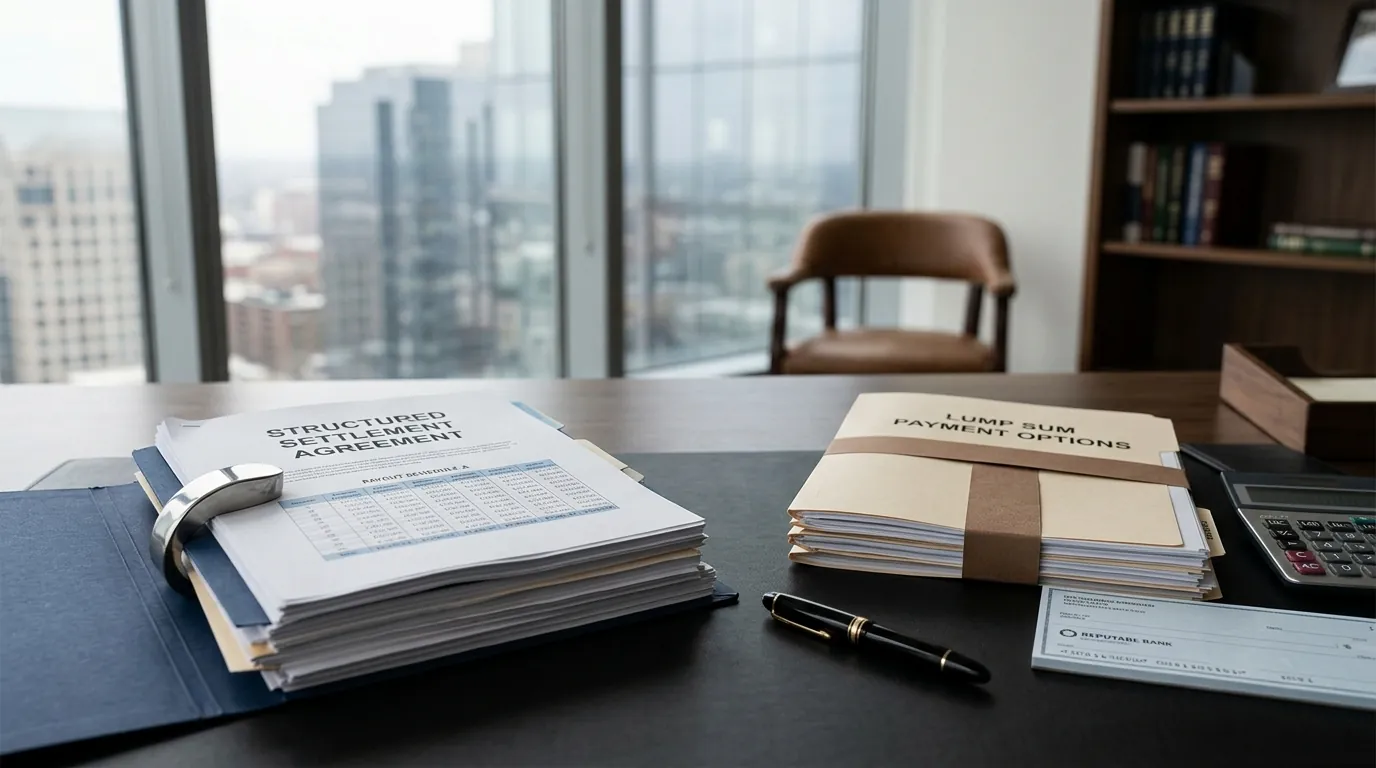
When your case settles, you have (in most cases) a choice: take the entire recovery as a single lump sum at closing, or take it as a stream of payments over years or decades via a structured settlement.
How Structured Settlements Work
The defendant (or their insurer) purchases an annuity from a life insurance company, which pays out to the plaintiff according to a schedule agreed at settlement. Payment schedules can include:
- Monthly for life.
- Guaranteed period (e.g., 20 years) followed by life-contingent payments.
- Milestone payments (age 18 for college, age 25 for house, retirement).
- Lump sums at intervals (e.g., $50K every 5 years).
Tax Treatment Advantage
Under IRC §104(a)(2) and §130, structured settlement payments arising from physical injury cases are entirely tax-free — including any growth over time. A $500K lump sum invested at 5% for 20 years pays taxes on gains. The same $500K in a structured settlement pays no tax on any of the growth, provided the structure was set up at settlement (not after).
Creditor Protection
Structured settlement annuities are generally protected from creditors, judgments, and (in most states) divorce. Lump sums placed in a bank account do not have this protection.
Where Lump Sum Wins
- Full flexibility for major purchases (house, business investment).
- Ability to invest for potentially higher returns than annuity rate.
- Simplicity — no ongoing dependency on annuity payer.
- Estate planning flexibility (structured settlements are somewhat rigid).
Where Structured Settlement Wins
- Catastrophic injuries requiring lifetime medical care — structured payments align with lifelong needs.
- Minors — structured settlements typically preferred by courts for minor beneficiaries.
- Financial discipline concerns — the annuity prevents impulsive spending.
- Tax-free growth on large recoveries.
- Predictable retirement-income planning.
Common Case Types Using Structured Settlements
- Catastrophic injury (spinal cord, TBI, amputations).
- Birth injury cases (cerebral palsy, Erb's palsy).
- Wrongful death (for surviving children or spouse).
- Minor plaintiff cases (court-required).
- Large recoveries where financial discipline is a concern.
The Selling Structured Settlements Market
Structured settlement holders sometimes sell their future payments to factoring companies for a discounted lump sum. This is regulated by state Structured Settlement Protection Acts requiring court approval. The discount rate is typically 10%–25% — meaning you receive far less than the payments were worth. Avoid unless truly necessary.
Hybrid Structures
Many settlements combine both approaches: a lump sum at closing to pay attorney fees, liens, and immediate needs, plus a structured component for long-term security. This is often the optimal choice for large recoveries.
The Bottom Line
Structured settlements offer tax-free growth, creditor protection, and financial discipline — but reduce flexibility. Lump sums maximize control and investment potential. Hybrid structures balance both. Discuss with your attorney and a settlement planning professional before signing.
At Instabridge Funding, we work with plaintiff attorneys across all fifty states — attorney-founded, non-recourse, and transparently priced. If your case is filed and you would like a fair pre-settlement offer, apply through our portal and your attorney will hear back within one business day.
Frequently asked questions
No, for physical injury cases under IRC §104(a)(2). All payments and growth are tax-free.
Not directly. Some contracts include limited flexibility, but generally the schedule is fixed at settlement.
You can sell future payments to a factoring company (with court approval), but you'll take a substantial discount (10%–25%).
Depends on circumstances. Structured settlement is often better for catastrophic injury, minors, or financial-discipline concerns. Lump sum for financially disciplined plaintiffs with clear investment plans.
The defendant or their insurer purchases from a life insurance company. Common carriers: New York Life, MetLife, Prudential, Berkshire Hathaway subsidiaries.
Yes. Structured attorney fees are a tax-planning strategy for plaintiff attorneys receiving large contingency fees.
State guaranty associations provide some protection, but only up to certain limits. Choose highly-rated annuity carriers.
Increasingly, especially for cases over $500K or involving catastrophic injury. Some settlements are entirely structured; many are hybrid.